

Profitable Insurance Business Strategies: Driving Sustainable Growth
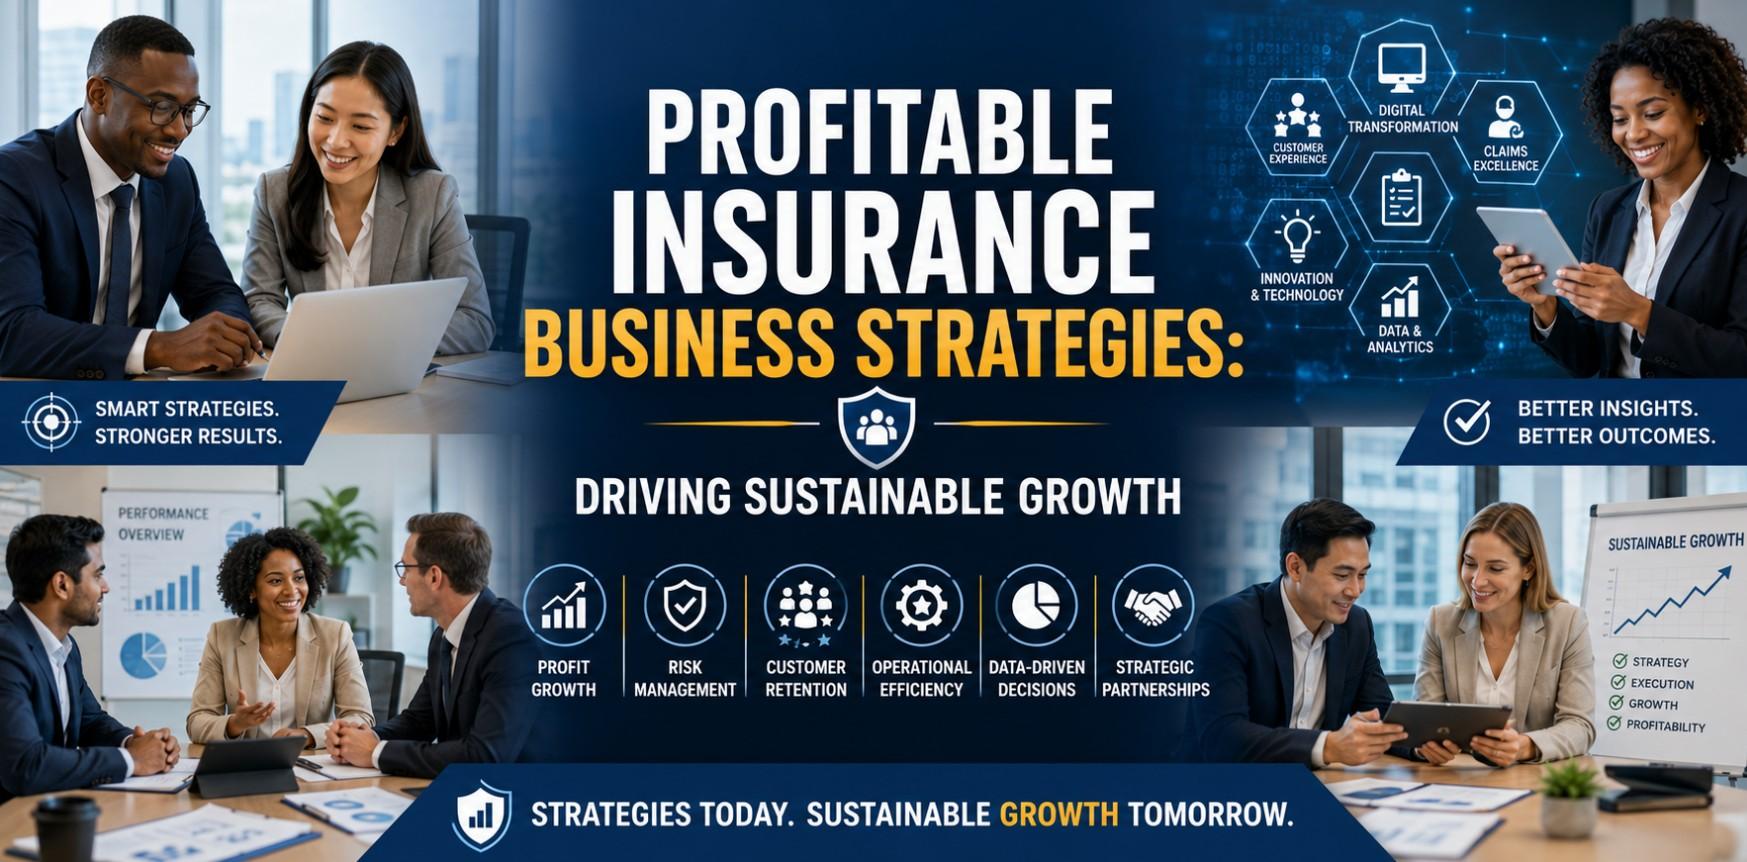
The insurance industry continues to evolve as customer expectations, technology, and market dynamics reshape how insurers operate. While demand for insurance products remains strong, profitability is no longer guaranteed through traditional business models alone. Insurance companies must adopt strategic approaches that balance customer acquisition, operational efficiency, risk management, and long term retention.
Organizations that focus on profitable insurance business strategies can strengthen their market position, improve customer satisfaction, and generate sustainable revenue growth. This article explores proven strategies that help insurance businesses increase profitability while remaining competitive in a rapidly changing marketplace.
Understanding Profitability in the Insurance Industry
Profitability in insurance extends beyond generating premium revenue. Successful insurers focus on maintaining a healthy balance between premium income, claims costs, operational expenses, and customer retention.
A profitable insurance business typically achieves the following objectives:
-
Maintains a strong underwriting performance
-
Reduces unnecessary operational costs
-
Improves customer lifetime value
-
Enhances risk assessment accuracy
-
Increases policyholder retention rates
By focusing on these core areas, insurance companies can create a foundation for consistent growth and long term success.
Strengthen Underwriting Practices
One of the most effective ways to improve profitability is through better underwriting. Accurate risk assessment allows insurers to price policies appropriately while minimizing exposure to high risk claims.
Modern insurance companies are increasingly using advanced data analytics and predictive modeling to evaluate customer risk profiles. These tools help underwriters make informed decisions based on real time information rather than relying solely on historical data.
Improved underwriting accuracy can significantly reduce claim losses and contribute directly to higher profit margins.
Invest in Digital Transformation
Digital transformation has become a critical factor in insurance profitability. Customers expect seamless online experiences, quick policy issuance, and efficient claims processing.
Insurance businesses that invest in digital platforms can streamline operations and reduce administrative costs. Automation can handle routine tasks such as policy renewals, document management, and customer inquiries, allowing employees to focus on higher value activities.
Benefits of digital transformation include:
-
Faster customer service
-
Reduced operational expenses
-
Improved data accuracy
-
Enhanced customer experience
-
Better decision making through analytics
Companies that embrace digital innovation often gain a competitive advantage while improving overall profitability.
Focus on Customer Retention
Acquiring new customers is often more expensive than retaining existing ones. Therefore, customer retention should be a central component of any profitable insurance strategy.
Building strong relationships with policyholders increases renewal rates and creates opportunities for additional product sales. Personalized communication, proactive support, and efficient claims handling can strengthen customer loyalty.
Insurance providers should regularly evaluate customer satisfaction levels and address pain points before they lead to policy cancellations.
A loyal customer base not only generates recurring revenue but also contributes to positive referrals and brand reputation.
Expand Cross Selling and Upselling Opportunities
Many insurance companies miss valuable revenue opportunities by focusing solely on single policy sales. Cross selling and upselling can significantly increase customer lifetime value.
For example, a client with auto insurance may also benefit from home, health, life, or business insurance products. By understanding customer needs and offering relevant coverage options, insurers can increase revenue without significantly increasing acquisition costs.
Successful cross selling requires:
-
Comprehensive customer data analysis
-
Personalized recommendations
-
Timely communication
-
Strong relationship management
When executed correctly, this strategy creates value for both the insurer and the customer.
Optimize Claims Management
Claims processing has a direct impact on profitability. Inefficient claims management can increase costs, delay settlements, and negatively affect customer satisfaction.
Insurance companies should focus on improving claims efficiency through automation, fraud detection technologies, and streamlined workflows. Faster and more accurate claims processing reduces administrative expenses while enhancing customer trust.
Additionally, implementing advanced fraud prevention measures can help insurers avoid significant financial losses. Even a small reduction in fraudulent claims can produce substantial profitability improvements over time.
Leverage Data Driven Decision Making
Data has become one of the most valuable assets in the insurance industry. Organizations that effectively collect, analyze, and utilize data can make smarter business decisions and identify new growth opportunities.
Data driven strategies can help insurers:
-
Identify profitable customer segments
-
Improve pricing accuracy
-
Predict claim trends
-
Enhance marketing effectiveness
-
Optimize product development
By transforming data into actionable insights, insurance companies can make informed decisions that support both growth and profitability.
Develop Strategic Partnerships
Strategic partnerships can open new distribution channels and expand market reach. Collaborating with financial institutions, brokers, technology providers, and industry associations can create mutually beneficial opportunities.
Partnerships enable insurers to access new customer segments while reducing marketing and acquisition costs. They can also provide access to innovative technologies and specialized expertise that improve operational performance.
A well structured partnership strategy can accelerate growth while maintaining profitability.
Enhance Employee Productivity and Training
Employees play a crucial role in the success of any insurance business. Investing in workforce development can improve service quality, operational efficiency, and customer satisfaction.
Training programs should focus on industry knowledge, customer service skills, compliance requirements, and emerging technologies. Well trained employees are better equipped to identify sales opportunities, manage risks, and deliver exceptional customer experiences.
Higher employee productivity often translates directly into improved business performance and stronger profit margins.
Conclusion
Achieving sustainable profitability in the insurance industry requires a combination of strategic planning, technological innovation, customer focused practices, and operational excellence. Companies that strengthen underwriting processes, embrace digital transformation, optimize claims management, and leverage data effectively are better positioned for long term success.
As competition continues to increase, insurers must continuously adapt to changing market conditions while maintaining a strong focus on efficiency and customer value. By implementing these profitable insurance business strategies, organizations can drive growth, improve financial performance, and build a resilient future.
Frequently Asked Questions
1. What is the most important factor in insurance profitability?
Accurate underwriting is one of the most important factors because it helps insurers assess risk correctly and price policies appropriately, reducing claim related losses.
2. How does digital transformation improve insurance profitability?
Digital transformation reduces operational costs, improves efficiency, enhances customer experience, and enables faster decision making through data analytics.
3. Why is customer retention important for insurance companies?
Retaining existing customers is generally more cost effective than acquiring new ones. Higher retention rates contribute to recurring revenue and increased customer lifetime value.
4. How can insurance companies increase revenue without acquiring new customers?
Insurance companies can increase revenue through cross selling and upselling additional insurance products to existing customers based on their needs and risk profiles.

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Greek